Our editorial team follows strict guidelines to ensure accuracy and objectivity. Learn more about our process.
How do annuities work? In two phases: you fund a contract with an insurance company, your money grows under defined terms, then you take income on a schedule you choose — including a paycheck for life if that is what you want.
Those mechanics matter before you sign anything. The product type determines how growth is credited, when payments can start, and how much access you have to the principal along the way. Below: what an annuity is, how the two-phase flow works, the main annuity types at a glance, and what to check before you fund.
Insurance Geek illustrates fixed, MYGA, FIA, and SPIA designs across 30+ A-rated carriers on the same premium, term, and state. If you are still choosing a product category, start with types of annuities — then return here for the mechanics.
Key Takeaways
Two phases. Every annuity has an accumulation phase (growth) and a distribution phase (income). The product type determines how long each lasts.
How growth works. Fixed and MYGA credit a guaranteed rate. Fixed indexed links growth to a market index without investing your premium in stocks. Variable uses subaccounts that rise and fall with the market.
How income works. You annuitize for a pension-like paycheck or take withdrawals while keeping a balance. Lifetime, joint, and period-certain options set how long payments run.
Liquidity. Most deferred contracts allow about 10% out per year without a surrender charge. Full early withdrawal triggers surrender penalties — and a 10% IRS penalty before age 59½ on the taxable portion.
What Is an Annuity?
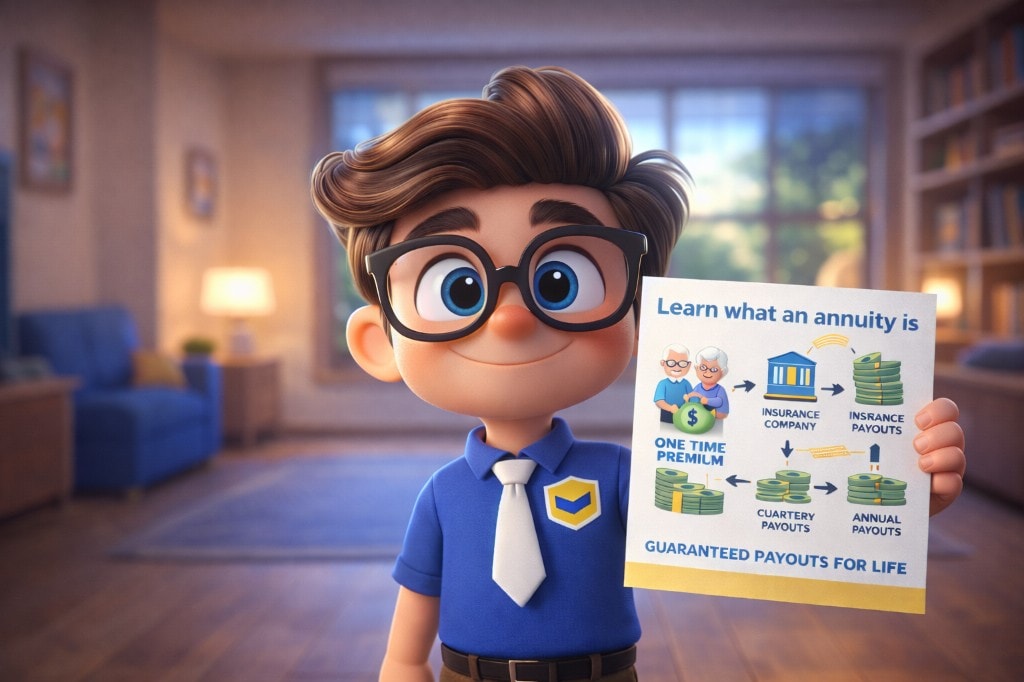
An annuity is a contract between you and an insurance company. You pay a lump sum or series of premiums; the carrier grows that money under the contract terms and pays it back to you as income — immediately or later, for a set period or for life.
Three roles show up on most contracts: the owner (who buys and funds it), the annuitant (whose life often drives payout calculations), and the beneficiary (who may receive remaining value at death). Annuities are insurance products, not bank deposits — guarantees depend on the issuing carrier.
How Do Annuities Work?
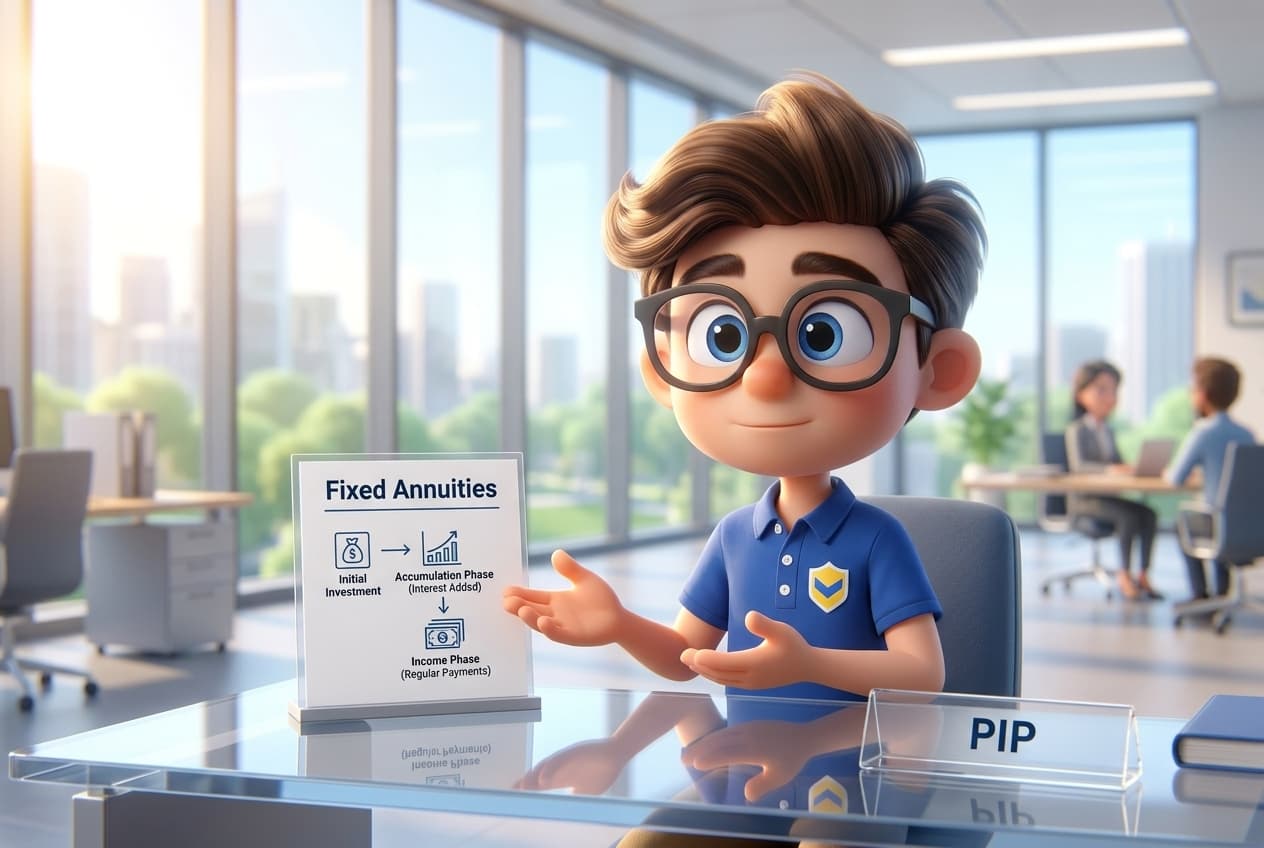
Every annuity follows the same basic flow. Here is how annuities work from funding through payout:
- You choose an annuity type and fund the contract with a lump sum or ongoing premiums.
- On deferred products, your money grows during the accumulation phase under the crediting terms you selected.
- When you are ready for income, you annuitize (convert account value to scheduled payments) or take systematic withdrawals.
- Payments run for the period or life you chose at purchase — monthly, quarterly, or annually.
The Accumulation Phase
During accumulation, your premium sits inside the contract and compounds under the terms you chose at purchase. On a fixed annuity, the carrier credits a declared interest rate. A MYGA locks one guaranteed rate for the full term you select — often three to ten years. A fixed indexed annuity links growth to a market index, but your premium is not invested in the stock market; principal is protected from market loss. A variable annuity allocates premium to subaccounts that rise and fall with the market — the one deferred type without principal protection.
Growth is tax-deferred across all deferred types: no annual tax on interest, index credits, or subaccount gains while the money compounds inside the contract. Most deferred contracts also allow about 10% of account value out each year without a surrender charge; full withdrawal during the surrender period triggers a penalty that steps down over time.
The Distribution Phase
Distribution is when accumulated value turns into income. You can annuitize — converting account value into guaranteed payments on a set schedule, like a personal pension — or take systematic withdrawals while leaving a remaining balance in the contract. Annuitization typically provides the strongest lifetime income guarantee; withdrawals keep flexibility but do not promise income you cannot outlive.
If you annuitize — or buy a single premium immediate annuity that skips accumulation — you choose how payments are structured: individual lifetime (paycheck for life), joint lifetime (continues for you or your spouse), period certain (fixed years of payments), or life with period certain (lifetime income with remaining years paid to a beneficiary if you die early). For a full comparison of how each option affects your monthly check, see annuity payout options.
Types of Annuities at a Glance
How annuities work depends on which type you buy. These are the main categories — each maps to the two-phase flow differently:
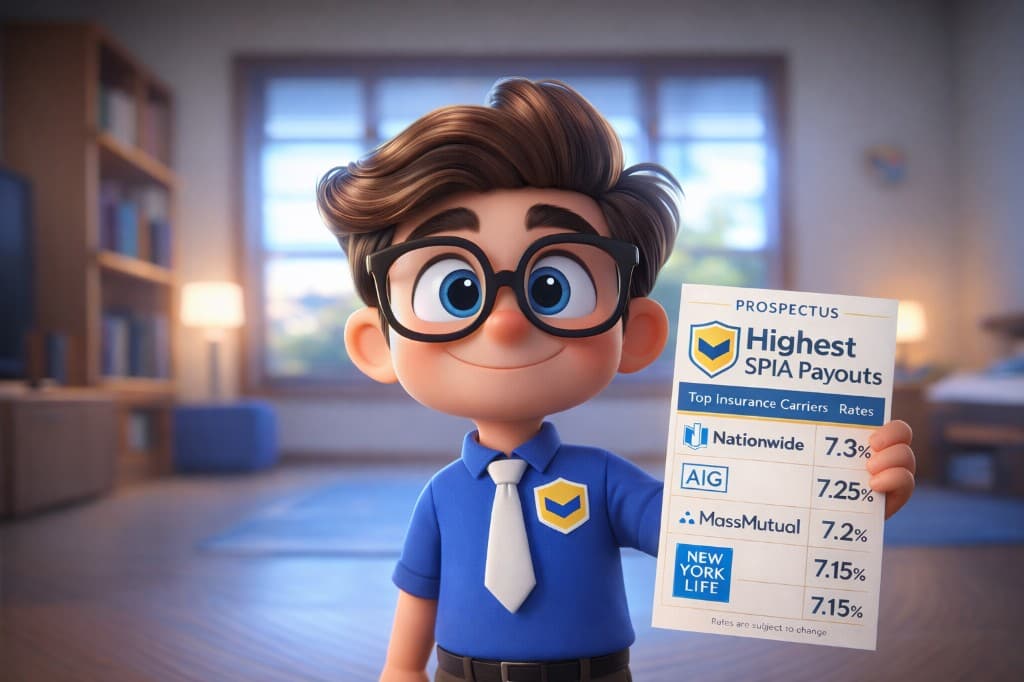
- Immediate (SPIA): Income starts within about a year of a single premium. No accumulation phase. See the SPIA guide.
- Deferred: Money grows first; you take income or withdrawals later. Fixed, MYGA, FIA, and variable are all deferred forms.
- Fixed / MYGA: Guaranteed rate; principal protected from market loss. See fixed annuity and MYGA guides.
- Fixed indexed: Index-linked crediting; principal protected; not invested directly in stocks. See the fixed indexed annuity guide.
- Variable: Subaccount growth with market exposure and no principal floor. Compare illustrations and disclosures with licensed help before you fund.
Expert Tip: The decision most people make too late
The annuitization decision is the one I see people rush through after spending months comparing accumulation products. Once you annuitize on a life-only option, that's permanent — the lump sum is gone and you own a monthly check. I spend as much time explaining payout options as I do explaining the product itself, because the structure you choose at income activation determines the outcome more than any accumulation feature.
—Brad Cummins, Insurance Geek Founder
Is an Annuity Right for You?
Most regret we see on annuities comes down to a phase mismatch — funding a deferred contract with money needed in three years, or annuitizing before exploring whether systematic withdrawals fit better.
This is right for you
- You want guaranteed or index-linked growth with tax deferral on money you can leave in place through the surrender period
- You need income you cannot outlive — now (SPIA) or later (deferred plus income rider)
- You understand the two-phase structure and have matched the product type to your timeline
- You are comparing carriers on the same product type, premium, and term — not mixing unrelated headline rates
This is not right for you
- You need full access to the principal within the next few years
- You want uncapped market returns without insurance contract surrender schedules
- You are shopping rates across different annuity types as if they measure the same thing
- You have not matched accumulation vs distribution to when you actually need the money
Before you commit
Before you fund any annuity, our agents walk clients through the same checks on every case:
- Phase: Are you in accumulation (grow first) or distribution (income now or soon)?
- Goal: Guaranteed growth, index-linked growth, or lifetime income — and when should income start?
- Liquidity: Can you leave the premium in place through the full surrender period without a full withdrawal?
- Same assumptions: Compare illustrations on the same premium, term, state, and product type — not a MYGA guarantee against an FIA cap.
- Taxes: Non-qualified growth is tax-deferred until withdrawal; qualified money follows retirement account rules. See annuity taxation for your situation.
There are dozens of annuity carriers and hundreds of product combinations. Finding an annuity is not the hard part. Narrowing them down to the right type and carrier for your goals is.
That's where we help. Fill out the form below and tell us what matters most — guaranteed rate, index strategy, income start date, or a combination. We'll compare the leading carriers and products available in your state, narrow the market down, and present you with a few best-fitting options. You don't have to sort through hundreds of annuities yourself — that's what we do every day.
Compare annuity illustrations
Compare MYGA rates, FIA caps, and SPIA payouts across 30+ A-rated carriers on the same premium, term, and state — one of our licensed agents runs the comparison and follows up with your options.
Conclusion
How do annuities work? Fund the contract, grow the money, then take income on the schedule you chose — that is the whole machine. Accumulation and distribution are the two phases every product shares; the annuity type determines how each phase behaves.
Once you know which phase you are in and which type matches your timeline, the carrier comparison gets straightforward. We run MYGA, FIA, and SPIA illustrations in your state on identical assumptions — so you are choosing between designs that fit the same goal, not headline numbers from different product types.
FAQ
About Brad Cummins
Brad Cummins is the founder of Insurance Geek and primary author of its educational content. Licensed since 2004, he brings over 21 years of experience structuring life insurance and IUL strategies for clients nationwide.
Fact checked by Ryan Wood
Ryan Wood is a licensed insurance professional and contributing advisor at Insurance Geek, serving as a fact checker and technical reviewer for life insurance and annuity content. First licensed in 2013, he brings more than 12 years of experience and holds licenses in over 40 U.S. states.