Our editorial team follows strict guidelines to ensure accuracy and objectivity. Learn more about our process.
Fixed indexed annuities sit in a gap most pre-retirees recognize: the guaranteed rate on a fixed annuity or CD feels low, but putting that money in equities means drawdowns they may not have time to recover from.
The product is built for that middle ground — index-linked growth with contractual protection against market loss. The real question is not how crediting works on paper; it is whether the surrender schedule, tax treatment, and carrier design fit money you can actually leave untouched.
Insurance Geek illustrates FIAs across 30+ A-rated carriers on the same premium, term, and state. Below: how crediting works, what to weigh before you fund, and who they fit — including who they do not.
Key Takeaways
Not an investment. A fixed indexed annuity is an insurance contract — your premium is not in the stock market.
Floor plus cap. Index down → 0% credited. Index up → you earn up to the cap, participation rate, or spread limit.
Three crediting levers. Cap rate, participation rate, or spread — each controls how much of an index gain reaches your account.
Long commitment. Surrender periods typically run 5–10 years; most contracts allow 10% out each year without a surrender charge.
Tax-deferred growth. Credited interest compounds without annual tax until withdrawal — strongest for non-qualified money after maxed 401(k) and IRA contributions.
How FIAs Credit Interest
Your premium is not in the stock market. At purchase, you pick an index from the carrier's menu — the S&P 500 is a common choice, but carriers offer others.
Most contracts credit on an annual point-to-point schedule: one year, measured from contract anniversary to anniversary. At each anniversary, the carrier compares where your index started and where it ended for that period.
- Index up: The carrier credits interest to your account. How much depends on your contract — a cap limits the maximum, a participation rate pays a percentage of the gain, or a spread subtracts a fixed amount before crediting.
- Index down or flat: You credit 0%. Your account value does not drop from index performance.
That credited interest adds to your account value and locks in at each anniversary. A bad year later cannot erase gains from a good year.
The Three Crediting Methods
| Crediting Method | How It Works | Example |
|---|---|---|
| Cap Rate | Maximum interest credited regardless of index gain | 9% cap with 18% S&P gain = 9% credited |
| Participation Rate | Percentage of index gain you receive | 70% participation with 12% gain = 8.4% credited |
| Spread | Percentage subtracted from index gain before crediting | 2% spread with 10% gain = 8% credited |
Current caps and participation rates by carrier are on the FIA rates page. Carrier rankings are on best fixed indexed annuity companies.
What Are My Index Choices?
Every carrier builds its own index menu. There is no standard list across the market.
Sample indexes on FIA contracts:
- S&P 500
- Dow Jones Industrial Average
- Nasdaq-100 (QQQ)
Many carriers also offer volatility-controlled and proprietary indexes. What you can select depends on the carrier, product, and state.
You do not start by picking an index off a list. You start with your goal — whether a fixed indexed annuity fits your timeline and what you are trying to accomplish. If it does, one of our licensed agents shops the top fixed indexed annuity carriers in the country and brings back the index options and contract designs worth comparing on your premium and term.
Already have an index in mind — QQQ, S&P 500, or something else? We find which carriers offer it in your state and run illustrations so you can see your real choices side by side.
Surrender Periods and Liquidity
FIAs are long-term contracts. Plan for money you will not need full access to for the length of the surrender schedule.
- Surrender period: Depends on the carrier and product — typically anywhere from 5 to 10 years. Full withdrawals during that window trigger surrender charges.
- Free withdrawal: Most contracts allow up to 10% of account value out each year without a surrender charge.
- Hardship waivers: Some contracts waive surrender charges for nursing home confinement, terminal illness, or disability — read the contract before you assume coverage.
- Before age 59½: A 10% IRS penalty applies to the taxable portion of withdrawals — separate from any carrier surrender charge.
If you need guaranteed access to principal on a specific date, a MYGA with a matching term or a bank CD is the cleaner structure. FIAs reward patience, not liquidity emergencies.
Tax Treatment
FIA growth is tax-deferred — credited interest compounds inside the contract with no annual tax until you take money out.
- Non-qualified: Funded with after-tax dollars. Only the gain is taxed on withdrawal, at ordinary income rates. Gains come out first; principal comes out tax-free once the gain is exhausted.
- Qualified: Funded with pre-tax dollars — typically an IRA or 401(k) rollover. Every dollar withdrawn is taxed as ordinary income. Required minimum distributions may apply at age 73.
Annuitization, inherited contracts, and the 10% pre-59½ penalty are covered on how annuities are taxed.
Expert Tip: What I look at before recommending an FIA
Before I recommend any FIA, I look at three things in order: how the carrier has maintained cap rates on in-force policies over the past five years, whether the income rider math actually holds up at the projected distribution date, and what the total cost is including any rider charges. The illustration looks great on every product — the difference shows up in what the carrier does five years into the contract when you're not shopping anymore.
—Brad Cummins, Insurance Geek Founder
Lifetime Income Rider
The main reason most people buy an FIA is the optional lifetime income rider. You fund the contract and let it grow during the deferral years — then, whenever you choose, you turn the rider on and the carrier sends you a paycheck for the rest of your life. It works like a personal pension you control the start date on.
Riders are available on an individual or joint basis. A joint rider keeps paying until the second death — you, your spouse, or both — depending on how the contract is structured.
The income payout is calculated from a separate benefit base, not your walk-away cash value. That base typically grows at a guaranteed roll-up rate during deferral — often 6%–8% compounded — before you activate income. Payouts on strong rider designs often land in SPIA territory: the advantage over buying a SPIA upfront is you get index-linked growth during the deferral years and decide later when to flip the income switch.
Riders typically cost 0.95%–1.25% of the benefit base annually. Skip the rider if your only goal is maximum accumulation with no lifetime income layer.
Is a Fixed Indexed Annuity Right for You?
Most regret we see on FIAs comes down to liquidity — buyers who needed the money before the surrender period ended. The product works well in a specific set of circumstances; outside those, a MYGA, a SPIA, or staying invested is usually the cleaner call.
This is right for you
- You’re near retirement and want principal protection with some upside
- You want a lifetime income option later (individual or joint)
- You can leave the money in place through the surrender period
- You’ve maxed qualified plans and want tax-deferred growth on after-tax money
This is not right for you
- You need full access to the money within 5–10 years
- You want uncapped market returns
- You’re not comfortable relying on an insurance carrier’s guarantees
- You don’t want rider fees or product complexity
Before you commit
Before you fund an FIA, our agents walk clients through the same checks on every case:
- Liquidity: Can you leave the premium in place through the full surrender period without needing a full withdrawal?
- Goal: Are you buying for accumulation, lifetime income, or both — and if income, individual or joint?
- Index: Do you have a preferred index, or do you want to see which top carriers offer the strongest options for your premium and term?
- Same assumptions: Compare illustrations on the same index, crediting method, and contract length — not headline rates on different indexes.
- Renewals: Look beyond today’s rates. How has the carrier treated caps and participation rates on existing contracts over time?
There are dozens of fixed indexed annuity carriers and hundreds of product and index combinations. Finding an annuity isn’t the hard part. Narrowing them down to the right ones for your goals is.
That’s where we help. Fill out the form below and tell us what matters most to you — whether that’s lifetime income, stronger caps and participation rates, consistent renewal rates, better liquidity, or a combination of those.
We’ll compare the leading fixed indexed annuity carriers and products available in your state, narrow the market down, and present you with a few best-fitting options. You don’t have to sort through hundreds of annuities yourself — that’s what we do every day.
Compare FIA illustrations
Compare fixed indexed annuity designs on the same premium, term, state, and index — one of our licensed agents runs the comparison and follows up with your options.
FAQ
Annuities
See which FIA design fits your goal.
A licensed expert compares index strategies and contract terms — not just the headline cap on the brochure.
Get My Illustration
About Brad Cummins
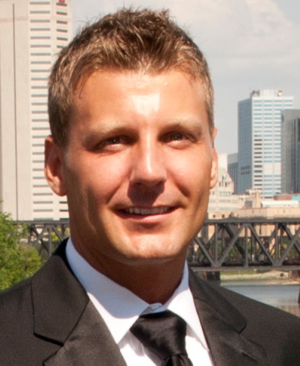
Brad Cummins is the founder of Insurance Geek and primary author of its educational content. Licensed since 2004, he brings over 21 years of experience structuring life insurance and IUL strategies for clients nationwide.
Fact checked by Ryan Wood
Ryan Wood is a licensed insurance professional and contributing advisor at Insurance Geek, serving as a fact checker and technical reviewer for life insurance and annuity content. First licensed in 2013, he brings more than 12 years of experience and holds licenses in over 40 U.S. states.