Our editorial team follows strict guidelines to ensure accuracy and objectivity. Learn more about our process.
Long-term care insurance cost comes down to two numbers: what care costs where you live, and what a carrier charges to cover that bill. Most people only ask about the second one. That's backwards—you can't judge a premium until you know the size of the benefit it has to buy.
This page starts with the care bill. The map and table below show 2025 state costs for in-home care, assisted living, and a private nursing-home room, from the CareScout Cost of Care Survey. Then we walk through what moves the premium and how to keep it in check.
Insurance Geek is an independent agency in Columbus, Ohio. I've been licensed since 2004, and we run long-term care insurance illustrations—traditional and hybrid—across 30+ A-rated carriers. We build the benefit around your state's numbers, not a national brochure.
Key Takeaways
Nursing home, national. A private room runs a median $129,575 a year, about $355 a day. A three-year stay tops $388,000.
In-home care, national. A 44-hour-a-week aide runs about $80,076 a year.
Assisted living, national. The median is about $74,400 a year.
Location swings it. A private nursing room in Oregon costs about $221,376 a year. In Texas and Missouri it's about $91,248.
Premium is a design choice. Age, health, daily benefit, benefit period, elimination period, and inflation protection set what you pay.
What long-term care costs in your state
Long-term care costs by state vary more than most people expect. The same private nursing room can cost more than twice as much in one state as in another. Hover over your state for in-home care, assisted living, and nursing-home costs. The color reflects the nursing-home figure: green states sit at the low end, red states at the high end.
The West Coast and the Northeast carry the heaviest bills. Oregon tops the nursing-home list, followed by Connecticut, New York, Hawaii, Washington, and Massachusetts. The South and lower Midwest are the cheapest places to need a facility—Texas, Missouri, Oklahoma, Arkansas, and Louisiana all land near the bottom.
Alaska is the one gap. CareScout didn't publish a private-room median there, so the map shows the semi-private figure instead.
Long-term care costs by setting
Where you receive care matters as much as where you live. Most people move through settings in order: help at home first, then assisted living, and a nursing home only if needs keep growing.
Medicare won't fund any of this over the long haul. It covers short skilled-nursing stays after a qualifying hospital admission, not months or years of custodial help. For the full rundown on benefit triggers and how policies pay, see what long-term care insurance is and how it works.
Long-term care costs by state: full table
This table converts the CareScout state medians into yearly and daily costs. Yearly numbers show what a full year of care costs; the daily nursing-home number is how most long-term care policies state their benefit.
| State | In-home care (per year) | Assisted living (per year) | Nursing home (per day) | Nursing home (per year) |
|---|---|---|---|---|
| Alabama | $61,776 | $53,100 | $289 | $105,444 |
| Alaska | $86,940 | $118,584 | Not reported | Not reported |
| Arizona | $86,940 | $75,000 | $376 | $137,244 |
| Arkansas | $57,204 | $55,644 | $265 | $96,720 |
| California | $91,524 | $84,000 | $499 | $182,136 |
| Colorado | $94,956 | $79,008 | $401 | $146,184 |
| Connecticut | $82,368 | $109,416 | $550 | $200,748 |
| Delaware | $80,076 | $91,200 | $497 | $181,584 |
| Florida | $73,212 | $67,320 | $400 | $146,004 |
| Georgia | $73,212 | $63,600 | $310 | $113,148 |
| Hawaii | $93,804 | $145,152 | $539 | $196,740 |
| Idaho | $88,092 | $62,100 | $400 | $146,004 |
| Illinois | $82,368 | $74,628 | $303 | $110,592 |
| Indiana | $80,076 | $67,668 | $339 | $123,912 |
| Iowa | $94,032 | $64,572 | $330 | $120,456 |
| Kansas | $77,220 | $71,700 | $298 | $108,768 |
| Kentucky | $74,364 | $66,336 | $370 | $135,048 |
| Louisiana | $59,484 | $61,956 | $266 | $96,912 |
| Maine | $101,820 | $98,460 | $490 | $178,848 |
| Maryland | $80,076 | $86,076 | $475 | $173,376 |
| Massachusetts | $91,524 | $115,200 | $520 | $189,804 |
| Michigan | $79,512 | $69,816 | $394 | $143,628 |
| Minnesota | $100,668 | $78,876 | $456 | $166,440 |
| Mississippi | $54,912 | $52,428 | $325 | $118,620 |
| Missouri | $75,504 | $64,800 | $250 | $91,248 |
| Montana | $86,940 | $72,900 | $315 | $114,972 |
| Nebraska | $82,368 | $76,200 | $303 | $110,592 |
| Nevada | $84,660 | $74,892 | $475 | $173,556 |
| New Hampshire | $91,524 | $96,300 | $442 | $161,328 |
| New Jersey | $86,940 | $104,520 | $475 | $173,376 |
| New Mexico | $68,640 | $71,400 | $350 | $127,596 |
| New York | $80,076 | $85,320 | $550 | $200,748 |
| North Carolina | $68,640 | $77,952 | $355 | $129,576 |
| North Dakota | $77,796 | $56,748 | $405 | $147,648 |
| Ohio | $77,796 | $73,236 | $342 | $124,668 |
| Oklahoma | $75,504 | $73,800 | $255 | $93,072 |
| Oregon | $91,524 | $82,500 | $607 | $221,376 |
| Pennsylvania | $77,796 | $77,760 | $450 | $164,256 |
| Rhode Island | $91,524 | $93,372 | $440 | $160,596 |
| South Carolina | $71,784 | $64,200 | $316 | $115,344 |
| South Dakota | $101,244 | $58,800 | $335 | $122,280 |
| Tennessee | $70,932 | $70,140 | $330 | $120,456 |
| Texas | $68,640 | $67,992 | $250 | $91,248 |
| Utah | $89,808 | $65,700 | $350 | $127,752 |
| Vermont | $102,960 | $103,164 | $511 | $186,336 |
| Virginia | $80,076 | $83,340 | $384 | $140,160 |
| Washington | $102,960 | $91,200 | $525 | $191,628 |
| West Virginia | $68,640 | $76,080 | $436 | $159,144 |
| Wisconsin | $82,944 | $78,480 | $405 | $147,828 |
| Wyoming | $105,252 | $63,900 | $359 | $131,076 |
Source: CareScout Cost of Care Survey, survey period July–November 2025. Annual figures are state monthly medians × 12. Daily nursing-home cost is the annual private-room median ÷ 365.
Find your state's daily nursing-home cost. That's your starting point for the daily benefit. If you expect to stay home as long as possible, the in-home care column is the more realistic target.
What drives long-term care insurance cost
There's no meaningful average premium for long-term care insurance. Two people the same age can pay very different amounts because they bought very different benefits. Carriers price two things: how likely you are to file a claim, and how much they'd pay out if you did.
Here's what moves the price, roughly in order of impact:
- Issue age: Premiums are set at the age you apply, so every birthday you wait adds to the price. Approval also gets harder in your late 60s and 70s, when cognitive and mobility screening start catching more applicants.
- Health history: Carriers look at prescriptions, recent diagnoses, mobility, and memory. A single new diagnosis between quotes can take traditional coverage off the table.
- Benefit size: A bigger daily benefit or a longer benefit period means more risk for the carrier. Two to three years of benefits costs far less than five years or lifetime coverage.
- Inflation protection: A compound inflation rider is one of the biggest line items, but a benefit bought at 55 has to stretch to cover care prices at 80.
- Elimination period: This is the waiting period before benefits start. Longer waits lower the premium.
Gender and marital status matter too. Many traditional policies charge women more because they file more and longer claims. Couples often get a discount, and shared-care riders let partners draw from each other's benefits.
See what LTC insurance would cost you
Once you know your state's care costs, the next step is pricing a benefit that covers them at your age and health. Enter a few details and we'll compare traditional and hybrid designs across carriers, then send you the illustrations.
Traditional vs. hybrid long-term care insurance cost
The two main product types charge you in very different ways, so their premiums aren't directly comparable. Compare what each one pays out, not just what it costs in year one.
Traditional LTC
Ongoing premiums buy a pure pool of care benefits. You usually get the most care coverage per dollar. The tradeoff: if you never need care, nothing comes back, and carriers can raise rates for an entire class of policyholders after you buy.
Hybrid life/LTC
A cash value life insurance or annuity policy with a long-term care benefit built in. It's often funded with one lump sum or 10 years of payments. Premiums are usually guaranteed, and if you never use the care benefit, your heirs get a death benefit.
Hybrids tend to show a bigger upfront number because you're also paying for life insurance. Traditional policies look cheaper on day one but carry the risk of future rate increases. The right comparison is total dollars in versus total benefit out under each scenario—care needed, care never needed, and care needed late.
How to lower long-term care insurance cost
You can't negotiate a carrier's filed rates. You can change what you're buying, and a few design choices move the premium more than switching carriers does.
- Apply earlier: Buying in your 50s or early 60s locks in a lower issue age while you're most likely to pass underwriting.
- Right-size the period: Most care needs are covered by two to four years of benefits. Save longer pools for strong family histories of dementia.
- Wait longer: A 90-day elimination period costs less than 30 days. Just know you'd cover about three months of care yourself, roughly $32,000 at the national nursing-home rate.
- Share the pool: For couples, one larger shared-care pool can cost less than two maximum individual policies.
- Go Partnership: In most states, a qualified Partnership plan shields assets from Medicaid spend-down, dollar for dollar, up to the benefits your policy paid.
Expert Tip: Size the daily benefit to your state, not the national number
Most people pick a round daily benefit that sounds big enough. I start from their state's nursing-home cost per day, subtract what Social Security and pensions would cover, and insure the gap. It's often a smaller benefit than they expected—and a smaller premium.
—Brad Cummins, Insurance Geek Founder
That gap method also shows how much coverage you really need. If your income already covers half of a day of care, you don't need to insure the whole day.
When LTC insurance doesn't make sense
Long-term care insurance isn't for everyone. For some people, paying premiums for decades costs more than the risk it covers.
Usually a good fit
- Savings and home equity you'd lose to Medicaid spend-down
- A spouse who depends on those assets after you need care
- Good health in your 50s or early 60s
- A premium you can keep paying into your 80s
Usually a poor fit
- Modest assets that a few months of care would exhaust
- Enough wealth to self-fund years of care without strain
- A recent diagnosis or cognitive decline that blocks underwriting
- A budget that would force you to drop the policy later
A policy you cancel at 72 was a costly placeholder. If you can't qualify for traditional coverage, some hybrids and short-term care plans are more lenient.
Most of our clients fall between those groups: too much to lose to Medicaid spend-down, not enough to shrug off a six-figure care bill. That's where coverage earns its cost, and why we price it as part of a broader retirement plan, not in isolation.
Are long-term care insurance premiums tax deductible?
Sometimes. Premiums on a tax-qualified long-term care policy count as medical expenses, up to an IRS limit based on your age. They only help if you itemize and your total medical costs exceed 7.5% of your adjusted gross income.
Self-employed people can often deduct qualified premiums without itemizing. C corporations can deduct premiums they pay for employees, including owners. Hybrid policies are treated differently, since only part of the premium pays for long-term care. The IRS updates the age-based limits every year, so confirm the current figures with a CPA before you count on a deduction.
Conclusion
The question isn't what long-term care insurance costs on average. It's what it costs to cover the care bill in your state, at the age and health you're in today. Start with your state's daily nursing-home and in-home care costs. Subtract the income you'll already have. Insure the gap.
From there, the premium comes down to design and carrier choice. The same benefit can land in very different price bands depending on inflation protection, benefit period, elimination period, and whether it's traditional or hybrid. As an independent agency, we price identical designs across carriers so you can see where the money actually goes.
Health is the part you can't control later. Most people who wait into their late 60s pay more, and some can no longer qualify.
Frequently Asked Questions
Long Term Care
Your state's care costs are the target. Let's price a policy that hits it.
We run traditional and hybrid LTC illustrations side by side on matching assumptions, across 30+ A-rated carriers.
See My Numbers
About Brad Cummins
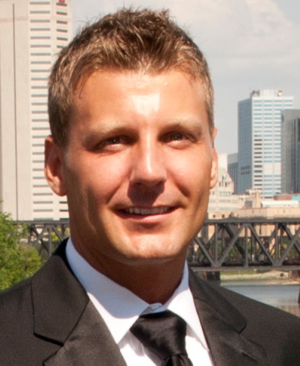
Brad Cummins is the founder of Insurance Geek and primary author of its educational content. Licensed since 2004, he brings over 21 years of experience structuring life insurance and IUL strategies for clients nationwide.
Fact checked by Ryan Wood
Ryan Wood is a licensed insurance professional and contributing advisor at Insurance Geek, serving as a fact checker and technical reviewer for life insurance and annuity content. First licensed in 2013, he brings more than 12 years of experience and holds licenses in over 40 U.S. states.