Our editorial team follows strict guidelines to ensure accuracy and objectivity. Learn more about our process.
Fixed annuities take market risk off the table. You deposit a premium, the carrier credits a declared or guaranteed interest rate for a set period, and your principal does not rise or fall with stocks. That predictability fits money you want to grow at a known rate — usually within five to ten years of retirement, or after you have maxed tax-advantaged accounts and still want tax-deferred accumulation.
The real question is not whether fixed annuities work — the mechanics are straightforward. It is whether the surrender schedule, tax treatment, and carrier strength fit money you can actually leave untouched for the full term.
Insurance Geek illustrates fixed annuity designs across 30+ A-rated carriers on the same premium, term, and state. Still comparing product types? Start with types of annuities — then use this guide for how fixed contracts work. Below: how crediting works, how fixed annuities are taxed, what liquidity looks like, and who they fit — including who they do not.
Key Takeaways
Declared or guaranteed rate. The carrier credits a set interest rate for a defined period — not linked to a stock market index.
Principal protected. Your account value does not fall because equities fell — the carrier assumes the investment risk behind the guarantee.
Tax-deferred growth. Interest compounds inside the contract with no annual tax bill until you withdraw.
MYGA is the common form. Most fixed annuities sold today lock one guaranteed rate for the full term — a multi-year guaranteed annuity, or MYGA.
Liquidity tradeoff. Surrender periods typically run 3–10 years; most contracts allow about 10% out each year without a surrender charge.
What Is a Fixed Annuity?
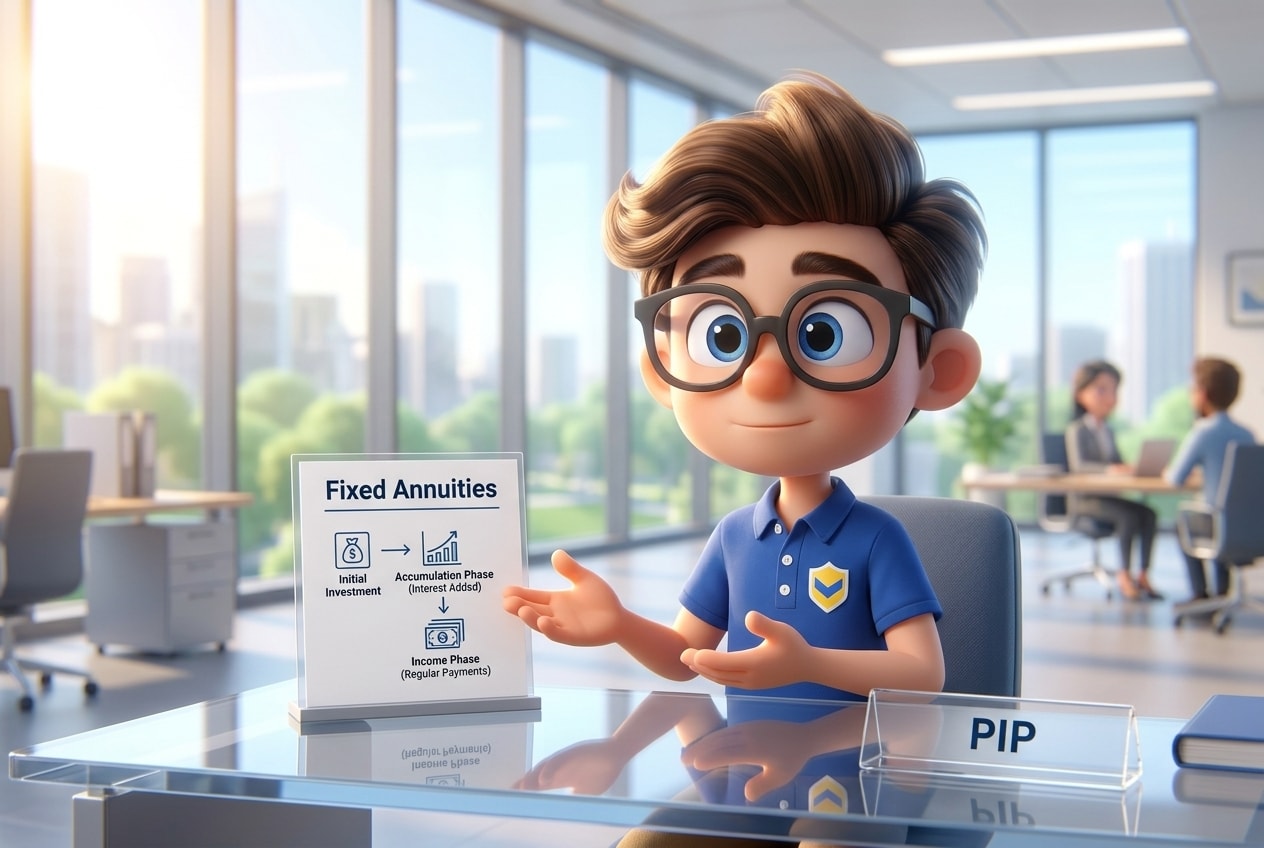
A fixed annuity is a contract between you and an insurance company. You deposit a lump sum — or in some cases a series of payments — and the carrier credits interest at a declared or guaranteed rate for the term you select. At maturity, you can withdraw the balance, roll into a new contract, or convert to a guaranteed income stream.
Unlike a fixed indexed annuity, a fixed annuity does not credit based on index performance. There are no caps, participation rates, or crediting methods — you know how your money earns on day one.
Fixed annuities are insurance products, not bank deposits. Guarantees depend on the issuing carrier and state guaranty associations within defined limits — not FDIC insurance.
How Fixed Annuities Work
Every fixed annuity follows the same basic flow:
- You select a term and fund the contract.
- The carrier credits interest at the declared or guaranteed rate for that period.
- Interest compounds inside the contract — tax-deferred on non-qualified money.
- At maturity, you withdraw, exchange into another annuity, or annuitize for income.
Most fixed annuities sold today are MYGAs — multi-year guaranteed annuities that lock one rate for the entire surrender period. Older deferred fixed contracts may reset declared rates annually after an initial guarantee. For a deeper look at the MYGA structure, see what is a MYGA.
Fixed Annuity Rates
Rates vary by term, carrier, premium band, and state. The rate you lock in at purchase is contractually guaranteed for the guarantee period — it does not move with the stock market during that time.
Current guaranteed rates by term and carrier are on the MYGA rates page. Carrier financial strength and rate maintenance are on best MYGA companies. Confirm live rates on your illustration before you fund — published tops shift monthly.
A higher rate from a lower-rated carrier is a different risk calculation than a slightly lower rate from an A-rated issuer — especially on longer terms. Position size relative to state guaranty association limits matters.
Tax Treatment
Fixed annuity growth is tax-deferred — interest compounds inside the contract with no annual tax until you take money out.
- Non-qualified: Funded with after-tax dollars. Only the gain is taxed on withdrawal, at ordinary income rates. Gains come out first; principal comes out tax-free once the gain is exhausted.
- Qualified: Funded with pre-tax dollars — typically an IRA or 401(k) rollover. Every dollar withdrawn is taxed as ordinary income. Required minimum distributions may apply at age 73.
That tax deferral is the main reason fixed annuities often beat bank CDs on equivalent terms — CD interest is taxed every year it is credited, even if you never touch the money. Annuitization, inherited contracts, and the 10% pre-59½ penalty are covered on how annuities are taxed.
Surrender Periods and Liquidity
Fixed annuities are long-term contracts. Plan for money you will not need full access to for the length of the surrender schedule.
- Surrender period: Usually matches the rate guarantee — a 5-year MYGA typically carries a 5-year surrender schedule. Full withdrawals during that window trigger surrender charges that step down over time.
- Free withdrawal: Most contracts allow up to 10% of account value out each year without a surrender charge.
- At maturity: The surrender period ends. You can withdraw the full balance, roll into a new contract, or annuitize — with no carrier-imposed penalty on full access.
- Before age 59½: A 10% IRS penalty applies to the taxable portion of withdrawals — separate from any carrier surrender charge.
If you need guaranteed access to principal on a specific date within the next few years, match the contract term to that timeline or keep the money liquid. Fixed annuities reward patience, not liquidity emergencies.
Expert Tip: What I look at before recommending a fixed annuity
Before I recommend any fixed annuity, I look at three things in order: whether the surrender period matches when the client can actually leave the money alone, whether tax deferral at their bracket makes the fixed rate worth the commitment over a CD, and whether the carrier rating fits the term length and deposit size relative to state guaranty limits. The highest rate on the sheet is not always the right answer.
—Brad Cummins, Insurance Geek Founder
Fixed Annuity vs CD
Shoppers often compare fixed annuities to bank CDs — same idea (guaranteed rate, defined term), different tax treatment and backing.
| Feature | Fixed annuity | Bank CD |
|---|---|---|
| Rate | Declared or guaranteed by contract term | Set by bank for term |
| Tax | Deferred until withdrawal | Taxed annually on credited interest |
| Backing | Insurance carrier + state guaranty limits | FDIC up to $250K |
| Liquidity | ~10% free annually; surrender charges during term | Early withdrawal penalty; full access at maturity |
| Contribution limits | None | None |
Fixed annuities typically publish higher headline rates than CDs on similar terms, and tax deferral widens the after-tax gap for many buyers. The tradeoff is carrier financial strength instead of federal deposit insurance — and a surrender schedule instead of simple maturity access.
Is a Fixed Annuity Right for You?
Most regret we see on fixed annuities comes down to liquidity — buyers who needed the money before the surrender period ended.
This is right for you
- You want a guaranteed rate with no market exposure for money you can leave in place through the surrender period
- You have maxed qualified retirement accounts and want tax-deferred growth on after-tax money
- You are within five to ten years of retirement and want a predictable foundation alongside market assets
- You are comparing bank CD rates and want the same commitment with tax-deferred compounding
This is not right for you
- You need full access to the principal within the next few years
- You want index-linked upside — a fixed indexed annuity fits that goal, not a declared-rate contract
- You have not maxed 401(k) and IRA contributions and still have room there
- You are under 59½ and may need access — the IRS penalty changes the math
Before you commit
Before you fund a fixed annuity, our agents walk clients through the same checks on every case:
- Liquidity: Can you leave the premium in place through the full surrender period without needing a full withdrawal?
- Term: Does the contract length match when you will actually need the money — or when you plan to roll or annuitize?
- Rate type: Are you locking a multi-year guarantee or accepting annual rate resets on a declared-rate contract?
- Carrier strength: Does the rating fit the term length and deposit size relative to state guaranty association limits?
- Same assumptions: Compare illustrations on the same premium, term, and state — not headline rates on different minimums.
There are dozens of fixed annuity carriers and hundreds of product combinations. Finding one is not the hard part. Narrowing them down to the right rate, term, and carrier for your goals is.
That's where we help. Fill out the form below and tell us what matters most — guaranteed rate, term length, carrier strength, or a combination. We'll compare the leading fixed annuity carriers and products available in your state, narrow the market down, and present you with a few best-fitting options. You don't have to sort through hundreds of annuities yourself — that's what we do every day.
Compare fixed annuity illustrations
Compare fixed annuity rates and contract terms on the same premium, term, and state — one of our licensed agents runs the comparison and follows up with your options.
Conclusion
A fixed annuity is the simplest deferred annuity design: a declared or guaranteed rate, principal protected from market loss, and tax-deferred compounding for money you can commit through the surrender schedule. The decision is whether your timeline and liquidity fit that structure — not whether the product is complicated.
If you want a rate you can quote on day one with no caps or index menus, a fixed annuity is the right category. If bank CDs feel too low but you still want principal protected from market loss and some index-linked upside, that is a fixed indexed annuity — different crediting, different tradeoffs. Pick the category first; then compare carriers on the same product type.
Once those pieces line up, carrier comparison is straightforward. We run fixed annuity illustrations in your state on identical assumptions — same premium, term, and withdrawal plan — so you are choosing between contracts that fit the same goal.
FAQ
Annuities
We'll find the right fixed annuity for your goal.
Work with Insurance Geek — MYGA or SPIA, a licensed expert shops carriers in your state and finds the strongest rate or payout for your timeline.
Get My Numbers
About Brad Cummins
Brad Cummins is the founder of Insurance Geek and primary author of its educational content. Licensed since 2004, he brings over 21 years of experience structuring life insurance and IUL strategies for clients nationwide.
Fact checked by Ryan Wood
Ryan Wood is a licensed insurance professional and contributing advisor at Insurance Geek, serving as a fact checker and technical reviewer for life insurance and annuity content. First licensed in 2013, he brings more than 12 years of experience and holds licenses in over 40 U.S. states.