Our editorial team follows strict guidelines to ensure accuracy and objectivity. Learn more about our process.
Oregon costs more than most states, and liability-only is not legal here. You also carry PIP and uninsured motorist. If you cause a crash, you pay the other driver; your medical bills start on PIP. Limits are in the table.
Key Takeaways
You need more than liability. PIP and uninsured motorist are required. Dollar amounts are in the table.
UM is not UIM. Uninsured motorist is mandatory. Underinsured motorist is optional — skip it and a driver on minimums can still leave you short.
Portland and I-5 cost more. Theft, density, and claim frequency. Ice and deer still hit off the interstate.
We quote appointed carriers only. Travelers, Nationwide, Liberty Mutual, Clearcover, Branch, Openly, and Steadily. Farmers and the captives write Oregon; they are not this stack.
Oregon Minimum Coverage Requirements
| Coverage | Minimum Required |
|---|---|
| Bodily injury liability (per person) | $25,000 |
| Bodily injury liability (per accident) | $50,000 |
| Property damage liability (per accident) | $20,000 |
| Personal injury protection (PIP) | $15,000 |
| Uninsured motorist bodily injury (per person) | $25,000 |
| Uninsured motorist bodily injury (per accident) | $50,000 |
Expert Tip: Required UM Is Not UIM
Oregon will not let you drop UM. It will not force you to buy underinsured motorist. After a crash, UM pays if the other driver has no insurance. UIM pays if they have a policy that is too small. Skip UIM and an at-fault driver on state-minimum liability can still leave you uncovered once their limits are gone.
—Brad Cummins
These limits apply to typical private passenger vehicles. Motorcycles, commercial, and fleet policies can differ.
What's Required vs. Optional
Oregon's required stack is liability plus PIP plus uninsured motorist. Optional coverages are what actually pay for your car and the gap when the other driver is insured but cheap.
Required:
- Bodily injury: Injuries you cause to other people. Not you. Not your passengers.
- Property damage: Their car or property. Oregon's PD floor is easy to blow past if you total a newer vehicle. Dollars are in the table.
- PIP: Your medical bills and lost wages after a crash, even if you caused it. See PIP coverage.
- Uninsured motorist: Required. You cannot waive it. See UM/UIM.
Not required but worth considering:
- Underinsured motorist: Offered, not mandated. This sits next to required UM when the other driver has a policy that is too small.
- Collision: Your vehicle in a crash. Lenders usually require it if you finance or lease. See collision.
- Comprehensive: Theft, ice, deer, vandalism. Those are ordinary Oregon claims, not rare ones. See comprehensive.
If you live in Portland or commute I-5, treat the table as the legal minimum, not the quote you want. Raise liability, add UIM, and buy more PIP if your health plan has a high deductible. If you finance the car, collision and comprehensive are not optional in practice.
Proof of Insurance & Vehicle Registration
Oregon wants proof at registration and at a stop. An ID card (paper or phone) or a declarations page works.
Insurers report coverage electronically. A lapse can trigger a notice even if you were not pulled over. Certain suspensions still mean an SR-22 for about three years.
Penalties for Driving Uninsured
| Violation | Consequence |
|---|---|
| First offense | License suspension; fines up to $1,000; possible impoundment |
| Subsequent offenses | Higher fines; longer suspension |
| Driving on a suspended license | Additional criminal penalties |
Reinstatement usually means proof of insurance plus fees and any court or DMV conditions.
Best Car Insurance Companies in Oregon
Insurance Geek quotes Oregon through Travelers, Nationwide, Liberty Mutual, Clearcover, Branch, Openly, and Steadily — wherever each is appointed. Bundling auto and home typically saves about 20% on that stack. Best fit is driving record, vehicle, and ZIP, not one name for the whole state.
Farmers, State Farm, Progressive, Geico, and Allstate still write a lot of Oregon paper, especially in the Portland metro and along I-5. Regional names show up east of the Cascades. We do not shop those here. There is no Oregon auto rate tracker on this site yet — treat those filings as market context, not a quote we can bind.
Cost of Car Insurance in Oregon
Oregon sits above the national midpoint for full coverage. Statewide dollars are on our average cost of auto insurance by state table.
Portland costs more because of density, theft, and how often people file. Salem and Eugene sit on the same I-5 pattern. Eastern Oregon is usually cheaper unless you drive a lot of highway miles. Ice, deer, and uninsured drivers are why comprehensive and UIM show up in real claims even when the statewide average looks “just a bit high.”
Use the car insurance calculator before you quote. The cheapest Oregon car insurance quote is the one that matches PIP, UM, UIM, and deductibles — not the one that drops PD or PIP to win the month.
Get Free Oregon Car Insurance Quotes
Run the quote at Oregon's required stack first — then raise PD and PIP if a Portland or I-5 crash would blow past the floors in the table. Connect your policy through Canopy Connect and we will check those limits against the appointed stack before renewal.
Don't have time to run a quote? Just send us your policy
Share your current policy declarations pages with us in two clicks. Takes about 30 seconds. We'll review your coverage, find gaps, and compare our carriers to your current policy.
Connect your policy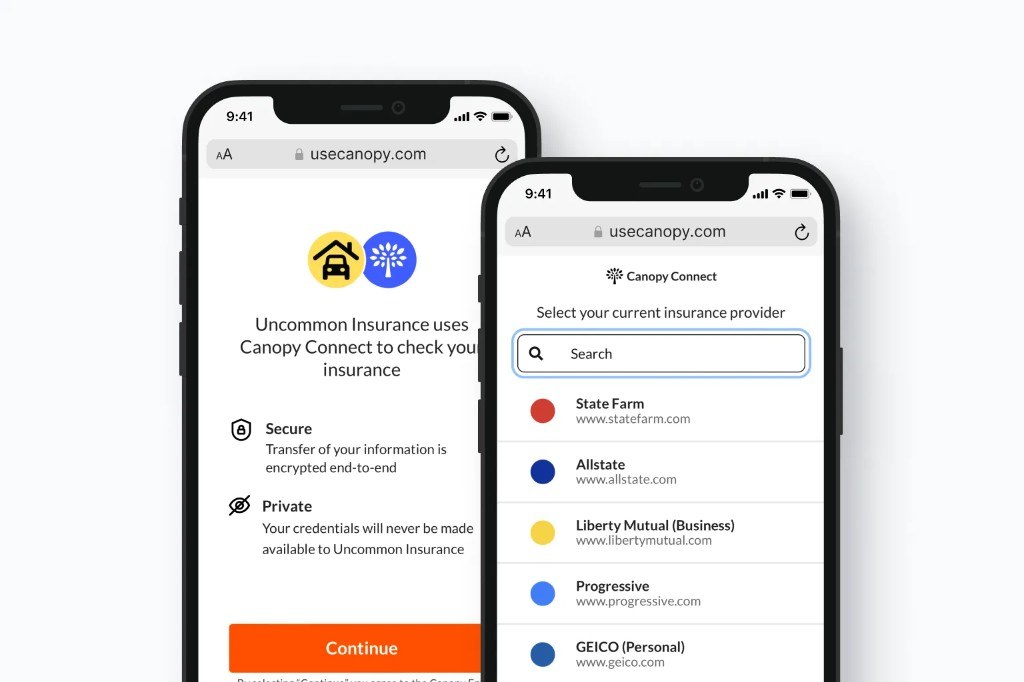
FAQ
About Brad Cummins
Brad Cummins is the founder of Insurance Geek and primary author of its educational content. Licensed since 2004, he brings over 21 years of experience structuring life insurance and IUL strategies for clients nationwide.
Fact checked by Brianna Baiocco
Brianna Baiocco runs P&C operations at Insurance Geek and fact-checks property and casualty content. Licensed since 2009, she brings over 16 years of experience in auto, home, renters, and commercial insurance.