Our editorial team follows strict guidelines to ensure accuracy and objectivity. Learn more about our process.
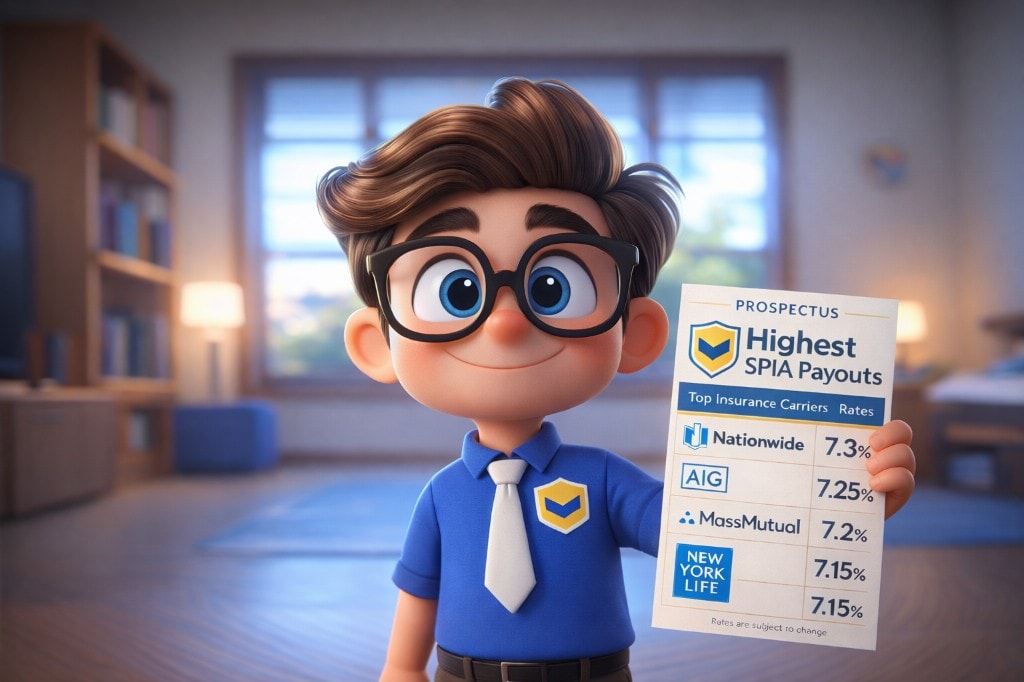
Looking for the best SPIA companies? The best company depends on the term, deposit amount, and payouts available in your state. No single carrier pays the most on every term. Insurance Geek compares 30+ highly rated carriers to find the strongest combination of payout and financial strength for your needs. Here are the SPIA companies worth comparing today.
Key Takeaways
5-year lead. Nationwide — $1,764.56/month on $250,000
7-year lead. Nationwide — $1,752.01. Athene did not quote this board.
10-year lead. Nationwide — $1,726.91
Same order this month. The $100,000 ranking matches the $250,000 ranking on all three boards.
These checks end. A period-certain SPIA is not lifetime income.
We shop it. We rerun the same design in your state — not one company's illustration.
| Term | Best company | Monthly on $250,000 |
|---|---|---|
| 5 years | Nationwide | $1,764.56 |
| 7 years | Nationwide | $1,752.01 |
| 10 years | Nationwide | $1,726.91 |
Ohio illustration, male age 65, single life, period certain, run November 15, 2026. Full boards: top SPIA rates.
Best 5-Year SPIA: Nationwide
- Monthly on $250k
- $1,764.56
- A.M. Best
- A+
- Period certain
- 5 years
- Leads the 5-year board on $100,000, $250,000, and $1,000,000
- Athene is second at $1,740.67 — $23.89 a month back
- Same five carriers, same order at $100,000
Nationwide pays the most on five years. Athene is second. Global Atlantic is third. EquiTrust led this board in May and is not in this top five.
The check lasts five years. After that it stops. If you need income past year five, this is the wrong design — or it is only the first illustration, not the only one.
When the 5-year fits
You want the highest check for a short guarantee. You understand it expires. You are comparing it to a 7-year and to a lifetime income rider, not locking the first quote you see.
Pros
- Highest 5-year payout on this snapshot
- A+ AM Best
- Leads $100,000, $250,000, and $1,000,000
Cons
- Check ends in five years
- Athene is close enough to shop
- Ohio snapshot — your state can reshuffle the board
Best 7-Year SPIA: Nationwide
- Monthly on $250k
- $1,752.01
- A.M. Best
- A+
- Period certain
- 7 years
- Leads 7-year on $100,000, $250,000, and $1,000,000
- Global Atlantic is second; Penn Mutual is third
- Athene did not quote this board
Nationwide takes seven years. Global Atlantic is second. Athene is not on this table — they quote 5- and 10-year on this snapshot, not 7-year.
Penn Mutual and Minnesota Life sit third and fourth. Corebridge is fifth.
When the 7-year fits
You can sit past five and you still want a period certain, not lifetime income. Or five-year Nationwide is not the design you need and you want the next board.
Pros
- Highest 7-year payout on this snapshot
- A+ AM Best
- Leads every premium column on this term
Cons
- Global Atlantic is close enough to shop
- Athene is absent on this term
- Still expires when the seven years end
Best 10-Year SPIA: Nationwide
- Monthly on $250k
- $1,726.91
- A.M. Best
- A+
- Period certain
- 10 years
- Leads 10-year on $100,000, $250,000, and $1,000,000
- Athene is second; Global Atlantic is third
- This check ends in 10 years — it is not lifetime income
Nationwide leads ten years. Athene is second. Ten years pays less per month than five. You are buying a longer guarantee, not a fatter check. And when year ten ends, the income stops.
Expert Tip: Period-certain SPIAs expire. Lifetime riders do not.
A SPIA on this page is period certain — the check ends when the term ends. Most cases I run, a fixed indexed annuity with a lifetime income rider pays as much or more and does not expire. That matters most at 10-year. I still quote the SPIA. I do not let it be the only illustration.
—Brad Cummins, Insurance Geek Founder
When the 10-year fits
You want a decade of guaranteed checks and you have compared it to a lifetime rider. You are not taking ten years because the number looks bigger — it does not.
Pros
- Highest 10-year payout on this snapshot
- A+ AM Best
- Leads every premium column on this term
Cons
- Pays less per month than the 5-year lead
- Income stops at year ten
- Athene and Global Atlantic are close enough to run
What we still check besides the payout
The monthly number is the start. Age, gender, state, refund options, and joint-life vs. single all move the leader. We still read AM Best and size the check against your state's guaranty limit — often $250,000 per insurer. Contract mechanics live on how annuities work. SPIA income is taxed as part exclusion, part ordinary income — read how annuities are taxed before you move the money.
We run the same process across annuity companies and the annuity rates board. The full carrier tables sit on top SPIA rates. If you are still choosing a product type, start at annuities.
That is the job. We have the board. You pick the term. We tell you who pays the most and whether a lifetime rider belongs next to it.
Who this is not for
A SPIA is the wrong tool if you need the premium back, you want the money to keep accumulating, or you have not decided how to protect a spouse. Life-only pays more and leaves nothing if you die early. Period certain and refund options cut the monthly check and protect heirs.
If you want a guaranteed rate for a set number of years — not a check — that is a MYGA. See best MYGA companies. If you want a floor plus index upside, start at FIA rates and best FIA companies.
Annuities
Carrier choice moves your monthly income.
We'll run your age, premium, and payout options and tell you which issuer leads for your facts.
See My Payout
Compare annuity illustrations
Compare MYGA rates, FIA caps, and SPIA payouts across 30+ A-rated carriers on the same premium, term, and state.
FAQ
Annuities
Carrier choice moves your monthly income.
We'll run your age, premium, and payout options and tell you which issuer leads for your facts.
See My PayoutAbout Brad Cummins
Brad Cummins is the founder of Insurance Geek and primary author of its educational content. Licensed since 2004, he brings over 21 years of experience structuring life insurance and IUL strategies for clients nationwide.
Fact checked by Ryan Wood
Ryan Wood is a licensed insurance professional and contributing advisor at Insurance Geek, serving as a fact checker and technical reviewer for life insurance and annuity content. First licensed in 2013, he brings more than 12 years of experience and holds licenses in over 40 U.S. states.