Our editorial team follows strict guidelines to ensure accuracy and objectivity. Learn more about our process.
Looking for the best infinite banking companies? For most people the choice is Penn Mutual or MassMutual. Penn Mutual has one adjustable loan you can explain, including what changes at policy year 11. MassMutual is the A++ option with cash value you can use early. The wrong contract is one whose loan you cannot explain. Insurance Geek illustrates both against your premium and how you plan to borrow. The cards below rank all seven.
Key Takeaways
Mutual companies. Policyholders own the company, so excess profits return as dividends rather than going to shareholders.
Ideal split. Put 30–40% in the base premium and 60–70% in paid-up additions. That builds cash value earlier and lowers commissions as a share of the premium.
Loan economics. What you pay to borrow is the loan rate, the spread on borrowed cash value, and whether you repay the interest or let it capitalize.
A++ ratings. MassMutual, Guardian, and Northwestern Mutual hold the highest AM Best tier. Most other carriers on this list hold A or A+.
Structure first. A properly structured policy at any of these seven carriers outperforms a poorly designed policy at the "best" company.
What Makes a Whole Life Policy Work for Infinite Banking
Infinite Banking requires a specific policy architecture that most standard whole life products don't provide. The evaluation framework I use covers seven factors in combination — no single factor determines fit, but all seven matter.
Mutual company structure means policyholders own the company. Excess profits return as dividends rather than going to external shareholders. This alignment is foundational — a stock company's obligations run to shareholders first, not policyholders.
Dividend history is the track record signal. A carrier that has paid dividends consistently through every economic cycle — including 2008 and the 2020 disruption — demonstrates the financial discipline that IBC depends on over a 30–40 year policy horizon. The 20-year whole life dividend interest rate history shows exactly how each major mutual carrier moved through the compressed rate era and where they stand today.
Loan interest rates determine the spread between what you pay to access your cash value and what the policy earns. Lower loan rates improve banking efficiency. Fixed loan rates provide certainty; variable rates introduce risk.
PUA rider flexibility determines how aggressively you can fund the policy beyond the base premium. Maximum PUA capacity relative to the base premium drives early cash value growth — the feature that makes the policy usable as a banking vehicle in the first few years rather than decade three.
Direct vs. non-direct recognition determines what happens to your dividend rate when you have outstanding loans. Non-direct recognition carriers pay the same dividend on the full cash value regardless of loans. Direct recognition carriers reduce dividends on the borrowed portion — but often offset this with higher overall dividend rates or lower loan interest rates.
Payment structure flexibility — 10-pay, 20-pay, paid-up at 65, single premium — affects how premium dollars flow and how quickly the policy matures.
Early cash value access varies significantly by carrier and product. Some policies have meaningful surrender value from year one. Others require five or more years before the cash value approaches premiums paid. For IBC, earlier access matters.
Best Infinite Banking Companies Ranked
Rank 1: 1. Penn Mutual
- AM Best
- A+ (Superior)
- Dividends Since
- 1847
- Dividend Rate
- 5.3% (Sep 2026)
- Adjustable loan rate 5.30% — direct recognition; rate can change annually
- Years 1–10: 5.30% loan charge vs. 4.65% dividend interest on the loaned portion (0.65% spread)
- Year 11+: preferred loan provision — loan rate and dividend interest on the loaned portion match (0% spread on that component; the loan is not 0%)
- Continuous dividend payments since 1847 — longest track record on this list
- 5.3% current dividend rate at 10–15% lower premiums than MassMutual for comparable benefits
Penn Mutual earns #1 because IBC lives or dies on loan economics. Penn offers one adjustable loan, and the rate is 5.30% as of September 2026. Direct recognition means only the loaned portion of cash value gets a lower dividend interest credit.
- Years 1–10: 5.30% loan charge vs. 4.65% dividend interest on the loaned portion. The spread is 0.65%. On $10,000 borrowed, that is roughly $65 of net drag on that slice for the year.
- Year 11+: The preferred loan provision kicks in. The loan rate and the dividend interest rate on the loaned portion match. If the loan rate is 5.30%, you pay 5.30% and get 5.30% credited on that slice. The spread goes to zero. The loan is not 0%. Only the net cost on borrowed money disappears.
- Lapse risk: Direct recognition does not waive loan interest. Unpaid interest capitalizes, the balance grows, and premiums still come due.
That year-11 flip is the long-term banking prize. Penn also has the longest dividend track record on this list, with continuous payments since 1847. Premiums run 10–15% lower than MassMutual for comparable death benefits at a 5.3% current dividend scale. The headline dividend scale and the loan-table dividend interest rates are different metrics. Run an illustration for your numbers.
When Penn Mutual Fits
- You plan to borrow actively and want the preferred loan provision at policy year 11.
- You want the longest dividend track record on this list.
- You are comparing Penn Mutual with MassMutual and want similar dividend performance at a lower premium.
Pros
- Preferred loan provision at policy year 11 eliminates spread on loaned portion
- One adjustable loan — no permanent fork at application
- 5.30% adjustable loan rate — competitive for direct recognition
- Continuous dividends since 1847 — longest track record on this list
- 5.3% dividend scale at 10–15% lower premiums than MassMutual
Cons
- A+ vs. A++ at MassMutual and Guardian
- Direct recognition years 1–10 carry 0.65% spread on loaned portion
- Adjustable loan rate can change annually
Rank 2: 2. MassMutual
- AM Best
- A++ (Superior)
- Dividends Since
- 1869
- Current Dividend
- 6.6% (As of May 2026)
- A++ AM Best rating — highest financial strength tier available
- Current dividend rate 6%, 15-year average 7.14%
- Offers both direct and non-direct recognition — rare flexibility
- 10, 20, age 65, and age 100 payment structures available
MassMutual earns #2 on financial strength: A++ from AM Best, dividends paid every year since 1869, and a 6.6% current dividend scale as of May 2026. Premiums run 10–15% higher than Penn Mutual for comparable benefits. That premium buys A++ strength and high early cash value. Once an illustration runs past policy year 11, Penn's preferred loan is the comparison to beat.
MassMutual loan options
You pick one loan type at issue. You cannot change it later.
- Adjustable loan: 5.77% as of September 2026. Non-direct recognition, so the full dividend is paid on all cash value whether you have a loan or not. The rate resets each policy anniversary. This is the usual choice for active borrowers.
- Fixed loan: 6.00%. Direct recognition. The dividend adjusts with loan activity and is not guaranteed. Model both before you choose the fixed loan.
High early cash value means loans can be available within days of issue. Borrowing that early, while cash value is still thin, needs a payback plan before the year-two premium hits. The policy loans guide covers that lapse risk.
When MassMutual Fits
- You want A++ financial strength.
- You want early cash value and will keep funding on schedule.
- You want the non-direct adjustable loan for frequent borrowing.
- Your horizon runs past policy year 11, so compare MassMutual with Penn on an illustration.
Pros
- A++ AM Best — highest financial strength tier
- Adjustable loan 5.77% with non-direct recognition
- HECV product — early cash value and fast loan access
- 10-pay, 15-pay, 100-pay, and pay-to-65 structures
- Continuous dividends since 1869 — nearly 160 years of payment history
Cons
- Loan type locked at issue — ALR vs FLR is permanent
- Premiums 10–15% higher than Penn Mutual for comparable performance
- HECV early loans require fast payback — year-two premium plus capitalizing interest increases lapse risk
- No year-11 preferred loan equivalent to Penn Mutual
Rank 3: 3. National Life Group
- AM Best
- A+ (Superior)
- Dividend Rate
- 5%
- Riders
- 10 options
- TotalSecure whole life allows additional premium payments to accelerate paid-up status
- Strong cash value guarantees with high death benefit protection
- 10 optional riders for policy customization
- A+ AM Best rating with mutual company structure
National Life Group's TotalSecure whole life is built for uneven cash flow. The required base premium stays low, and extra premium can accelerate paid-up status.
- Flexible funding: Business owners, commission earners, and seasonal income can add premium in strong years without a high required base.
- Dividend rate: 5% trails MassMutual's 6.6%. A+ strength and paid-up additions flexibility matter more when the constraint is the minimum premium, not the highest dividend.
- Riders: 10 optional riders, the broadest customization menu on this list.
When National Life Group Fits
- Your income varies and you need a low required premium.
- You want paid-up additions flexibility and cash value guarantees.
- You want a low base premium with room to fund more in strong years.
Pros
- TotalSecure allows additional premium to accelerate paid-up status
- Low required base premium — flexible for variable income situations
- 10 optional riders — tied for most on this list
- A+ AM Best rating
Cons
- 5% dividend rate trails MassMutual and Guardian
- Loan rates calculated at time of loan — variable rate introduces uncertainty
- Less recognized in IBC practitioner community than MassMutual or Penn Mutual
Rank 4: 4. Lafayette Life
- AM Best
- A+
- S&P Rating
- AA
- Recognition
- Non-direct
- Non-direct recognition — full dividend rate on entire cash value regardless of outstanding loans
- A+ AM Best and AA S&P dual ratings
- Primary draw for IBC practitioners who anticipate frequent policy loans
- Consistent 5.25%–5.50% dividend performance
Lafayette Life is the non-direct recognition company on this list. The full dividend is paid on all cash value, including the portion that backs a loan.
- Non-direct recognition: Borrowed cash value earns the same dividend as unborrowed cash value. That is the reason to use Lafayette when loans are frequent and large.
- Dividend scale: About 5.25%–5.50%. That trails MassMutual and Guardian if you rarely borrow.
- Ratings: A+ from AM Best and AA from S&P.
When Lafayette Life Fits
- You expect frequent or large policy loans.
- You want the full dividend kept on the entire cash value.
- You have already modeled how often you will borrow.
Pros
- Non-direct recognition — full dividend regardless of outstanding loans
- A+ AM Best and AA S&P dual ratings
- The non-direct recognition option on this list for frequent borrowers
- Consistent dividend performance at 5.25%–5.50%
Cons
- Dividend rate trails MassMutual and Guardian when you borrow rarely
- Fewer payment structures than MassMutual
- The non-direct advantage shrinks if loans are occasional
See Which Carrier Fits Your IBC Plan After the Rankings
Your premium, how often you borrow, and your paid-up additions split decide which mutual wins. We illustrate the carriers on this list for your numbers.
Rank 5: 5. Foresters Financial
- AM Best
- A (Excellent)
- Max No-Exam
- $400K
- Structure
- Fraternal benefit society
- Only carrier on this list offering participating whole life without a medical exam up to $400K
- Fraternal benefit society structure — similar policyholder alignment to mutual companies
- Guaranteed Insurability Rider allows coverage increases without future underwriting
- Consistent dividend performance competitive with major mutual carriers
Foresters Financial is the access option on this list. It is the only carrier here that offers participating whole life, the product IBC needs, with no medical exam up to $400,000.
- No exam: Useful when health would complicate full underwriting, and also worth illustrating next to a fully underwritten policy if you simply want to skip the exam.
- Fraternal structure: Not a mutual company. Excess profits still return to members, and the dividend commitment follows that structure.
- Guaranteed insurability: Coverage can increase later without new underwriting. That fits a client who expects premium capacity to grow.
When Foresters Fits
- Health issues make traditional underwriting unlikely.
- You want to start a participating whole life policy without a medical exam.
- You expect to add coverage later and want that increase guaranteed.
Pros
- Only participating whole life no-exam option up to $400K on this list
- Guaranteed Insurability Rider for future coverage increases without underwriting
- Fraternal benefit society structure aligns with policyholder interests
- Accessible entry point for clients with health concerns
Cons
- $400K no-exam limit — higher coverage requires full underwriting
- Fraternal society structure differs from traditional mutual company
- Fewer payment structure options than MassMutual
Rank 6: 6. Guardian Life
- AM Best
- A++ (Superior)
- S&P Rating
- AA+
- Dividend Rate
- ~5.75%
- A++ AM Best and AA+ S&P — elite dual financial strength ratings
- Offers both direct and non-direct recognition — same rare flexibility as MassMutual
- 10-pay limited pay structure excels for accelerated IBC accumulation
- 5.75% dividend rate with decades of consistent performance
Guardian is the other A++ choice next to MassMutual, and it is the strongest 10-pay design on this list.
- Financial strength: A++ from AM Best and AA+ from S&P at the same time. Guardian and MassMutual are the two carriers here that clear that bar.
- Loan recognition: Both direct and non-direct recognition are available, same rare choice as MassMutual. You can match the loan design to how often you expect to borrow without switching companies.
- 10-pay: Premiums are concentrated into 10 years. Paid-up additions build faster, and the policy needs less ongoing premium sooner than a lifetime-pay design. This is the fit when current cash flow is strong and you want to front-load the banking function.
When Guardian Fits
- You want elite financial strength alongside MassMutual.
- You want both recognition methods inside one carrier.
- You have the cash flow to fund a 10-pay and want accumulation front-loaded.
Pros
- A++ AM Best and AA+ S&P — dual elite financial strength ratings
- Both direct and non-direct recognition available — unique flexibility like MassMutual
- 10-pay limited pay structure ideal for accelerated IBC accumulation
- 5.75% dividend rate with decades of consistent performance
- Active IBC strategy promotion among Guardian agents
Cons
- Career agent distribution means policy design quality varies by advisor
- Premium pricing reflects elite financial strength positioning
Rank 7: 7. Northwestern Mutual
- AM Best
- A++ (Superior)
- Dividends Since
- 1872
- Dividend Rate
- 5.75% (2026)
- Direct recognition only — net borrow cost is dividend scale plus admin charge, not the headline loan rate
- Fixed loan or variable Market Loan Rate — net cost similar under Northwestern's direct recognition rules
- Dividends paid every year since 1872 — true mutual company owned by policyholders
- A++ AM Best and AAA Fitch — among the strongest balance sheets in the industry
- 5.75% dividend scale for 2026 — slowest recovery from 2006 peak on our dividend history chart
Northwestern Mutual earns #7 on brand scale and balance sheet, not on IBC loan math. A++ from AM Best, dividends every year since 1872, and a mutual company owned by policyholders. The 5.75% dividend scale for 2026 is real participating whole life. It trails MassMutual, Guardian, and Penn on current declared rates, and it recovered more slowly from the low-rate era than those peers on our 20-year dividend history.
Northwestern Mutual policy loans
Northwestern uses direct recognition only. The contract loan rate is not the number that drives the banking math.
- Net borrow cost: Dividend credit on the loaned portion adjusts to the loan rate minus an administrative charge. Unborrowed cash value still earns the full dividend scale. Northwestern's own framework puts the cost of borrowing at roughly the dividend scale plus that charge, often 0.25%–0.65% depending on policy age.
- Loan choices: A fixed loan rate or a variable Market Loan Rate. Under direct recognition, those options often land at a similar net cost because the dividend adjustment moves with the loan charge. Illustrate both. The listed rate is not the IBC result.
- Early access: Northwestern's own materials often cite 10 or more years before standard designs support meaningful loans. Heavy paid-up additions, and limited pay when cash flow allows, can shorten that. This is not the carrier to pick for high-early-cash-value access.
When Northwestern Mutual Fits
- You already work with a Northwestern advisor and want participating whole life inside that relationship.
- You care more about A++ brand recognition and mutual structure than the highest dividend scale.
- You borrow occasionally on a long horizon, rather than running frequent loan cycles.
Pros
- A++ AM Best and AAA Fitch — elite financial strength
- True mutual company — dividends every year since 1872
- Direct recognition rules are transparent once modeled on illustration
- Strong brand trust for clients already in the Northwestern ecosystem
Cons
- Direct recognition only — no non-direct option for frequent borrowers
- 5.75% dividend scale trails Penn and MassMutual on current declared rates
- Net borrow cost runs dividend scale plus admin charge — headline loan rate misleads
- Captive agent distribution — harder to compare against independent-market IBC designs
- Standard designs emphasize long cash-value build — not early banking access without heavy PUA structure
Direct vs. Non-Direct Recognition: What Actually Matters
The direct vs. non-direct label gets over-weighted. What matters is loan rate, spread on borrowed cash value, and whether you pay loan interest back or let it capitalize.
Direct recognition adjusts dividend interest on the loaned portion only. Penn Mutual uses direct recognition on its single adjustable loan — 0.65% spread in years 1–10, then 0% spread from policy year 11 under the preferred loan provision. MassMutual's fixed loan (6.00%) is also direct recognition.
Non-direct recognition pays the same dividend on all cash value regardless of loans. Lafayette Life works this way on the whole policy. MassMutual's adjustable loan (5.77% as of September 2026) does too, but only if you choose that loan at issue. Northwestern Mutual is direct recognition only. Borrowed cash value there earns an adjusted credit, not the full dividend scale.
Neither structure waives loan interest. Unpaid interest adds to the loan balance; premiums still come due. That combination — not the recognition label — is what creates lapse risk.
For most clients comparing the top two carriers: Penn rewards a long horizon with year-11 zero spread on one simple loan. MassMutual rewards early cash value through HECV but forces a permanent ALR vs FLR choice at application. Run illustrations on both with your actual borrowing pattern before deciding. Full loan breakdown: infinite banking policy loans.
Key Policy Design Elements for IBC
Carrier selection matters — but policy structure determines whether the banking strategy actually works. Three design elements drive IBC efficiency more than anything else.
Paid-up additions rider allocation is the primary lever. The ideal IBC policy allocates 30–40% to the base premium and 60–70% to paid-up additions. This structure accelerates early cash value, reduces agent commissions as a percentage of total premium, and creates the immediate usable cash value that makes the policy function as a banking vehicle in years one through five rather than decade three.
MEC compliance sets the funding ceiling. The policy must stay below the Modified Endowment Contract threshold — crossing it changes the tax treatment of loans and withdrawals fundamentally. Every dollar of PUA funding should be calibrated to maximize accumulation while staying below the MEC limit.
Loan provision matching to anticipated use. If you plan to borrow frequently, loan rate and net spread matter more than the recognition label — and you need a payback plan so interest does not capitalize against a thin early cash value base. If you borrow occasionally, dividend scale and cash value growth rate matter more. The policy structure should reflect your actual banking behavior, not a generic IBC template.
Expert Tip: Keep a carrier whose loan you can explain
The carrier that matters is the one whose loan you can explain. You should know the rate, what the dividend does on the money you borrowed, and whether that rule changes in a later policy year. If you cannot say that out loud, do not fund the policy.
—Brad Cummins, Insurance Geek Founder
FAQ
Infinite Banking
Carrier rankings narrow the field — next step is illustrations on the mutuals that match your premium, timeline, and how you plan to use loans.
Compare carriers
About Brad Cummins
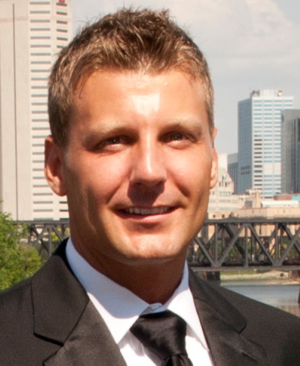
Brad Cummins is the founder of Insurance Geek and primary author of its educational content. Licensed since 2004, he brings over 21 years of experience structuring life insurance and IUL strategies for clients nationwide.
Fact checked by Ryan Wood
Ryan Wood is a licensed insurance professional and contributing advisor at Insurance Geek, serving as a fact checker and technical reviewer for life insurance and annuity content. First licensed in 2013, he brings more than 12 years of experience and holds licenses in over 40 U.S. states.